A supply chain management perspective
by aBCD Consulting
What the LIFO method is and how it works
The LIFO (Last In, First Out) method is an inventory management and valuation approach under which the most recently purchased or produced goods are the first to be used or sold. The underlying logic may seem counterintuitive compared with the natural physical flow of goods, but it has a clear rationale from an accounting and tax perspective: when prices are rising, assigning the costs of the most recent (and therefore higher-priced) purchases to goods sold reduces reported profit and, as a result, the tax burden. It is important to distinguish LIFO as an accounting and valuation method from LIFO as a physical logic for moving goods in the warehouse. The two concepts do not always coincide, and in logistics practice it is essential to clarify which meaning is being applied, to avoid operational confusion and discrepancies between the reality of the warehouse and how it is represented in management systems.
LIFO in the valuation of warehouse inventory
In accounting terms, under LIFO, closing inventory is valued at historical prices (those of the oldest purchases), while the cost of goods sold is based on the most recent purchases. In periods of inflation, this results in a higher cost of goods sold and lower reported profit, with a direct effect on the company’s tax burden. It can therefore be advantageous from a tax perspective, but at the same time it tends to understate the real value of warehouse inventory, making the balance sheet less representative of the company’s actual financial position. From a regulatory standpoint, LIFO is permitted under Italian national accounting standards (OIC) but not under IFRS (International Financial Reporting Standards). This limits its use to companies that apply Italian accounting standards, effectively ruling it out for listed companies or internationally active businesses subject to international standards. Before adopting it, it is therefore essential to carefully assess your regulatory and tax context, ideally with the support of a specialist advisor.
Advantages and disadvantages of the LIFO method
Like any inventory management method, LIFO has strengths and limitations that should be understood before adopting it. The main advantage is the ability to optimise the tax burden during inflationary periods: by assigning the costs of the most recent (and generally higher-priced) purchases to goods sold, taxable profit is reduced, with a direct benefit for cash flow. Secondly, LIFO provides a more realistic match between recent purchase costs and current sales revenue, making short-term operating margins easier to read.
On the downside, the most obvious limitation is the understatement of inventory on the balance sheet: stock is valued at historical prices that may differ significantly from current market values, reducing how accurately the balance sheet reflects the company’s assets. Added to this is the IFRS regulatory constraint mentioned above and, at an operational level, the risk that a LIFO logic applied physically in the warehouse may create inefficiencies in stock rotation, particularly for products with expiry dates or that are prone to deterioration.
Differences between LIFO, FIFO and other valuation methods
Understanding the differences between LIFO, FIFO and weighted average cost is essential to choose the method best suited to your operational and tax context. The FIFO (First In, First Out) method follows the opposite logic: the first goods in are also the first out, so inventory is valued at the most recent prices and the cost of goods sold reflects the oldest purchases. In periods of inflation, FIFO produces higher reported profit than LIFO (and therefore a higher tax burden), but it gives a more up-to-date picture of the company’s assets, in line with market values. It is also the only method permitted under IFRS, which makes it mandatory for companies subject to international accounting standards. The weighted average cost method sits somewhere in between: it calculates an average unit value, weighted by quantity, across all purchased batches, smoothing out price fluctuations and providing a more stable representation of inventory over time. It is widely used by companies with large purchase volumes and high price variability, and it is permitted under both OIC and IFRS.
The choice between the three methods is therefore not merely technical: it requires an integrated assessment of the business sector, the applicable tax regime, the nature of the goods handled and the company’s strategic objectives.
Practical examples and calculations using the LIFO method
In a warehouse that periodically receives deliveries of the same product at prices that vary over time, the LIFO method means each withdrawal draws first on the most recently received batch. The cost recorded for goods sold therefore reflects the latest prices, while inventory on the balance sheet retains the value of the earliest purchases. This mechanism becomes particularly relevant in sectors where purchase prices change frequently , such as raw materials, semi-finished goods and commodities, directly affecting the financial result for the year and pricing decisions. The difference compared with FIFO can be significant even with the same volumes handled: during periods of high input inflation, LIFO can produce a considerably higher cost of goods sold and lower profit, with effects not only on taxation but also on the profitability indicators used to assess company performance.
Applications and storage solutions based on the LIFO method
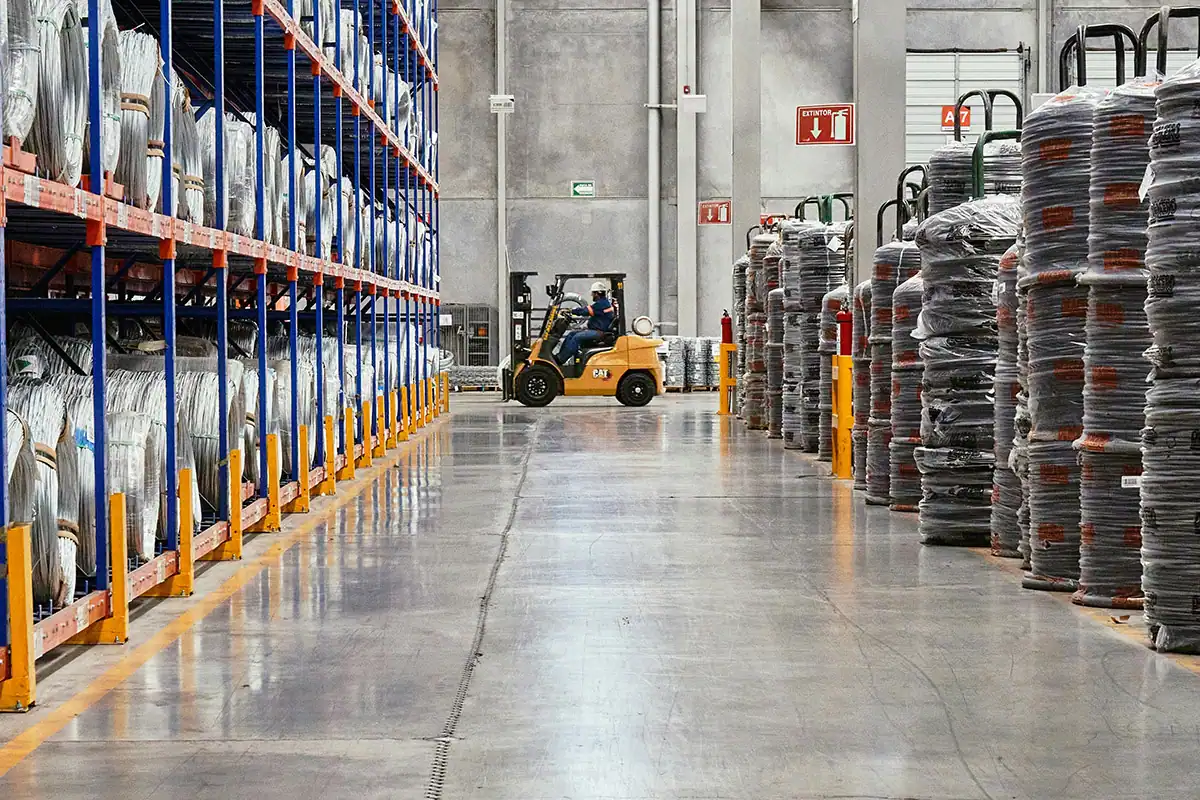
At a physical and organisational level, the LIFO method is applied in specific storage contexts, particularly where the chronological rotation of products is not a critical factor and storage density or operational simplicity of flows takes priority. Push-back racking systems, block stacking and drive-in racking are typical examples of storage systems that physically follow a LIFO logic: loading and picking take place from the same side, which naturally gives access to the most recently stored items.
This configuration maximises storage capacity in limited space and is particularly common in manufacturing, in the distribution of non-perishable materials and in the logistics of products with a long shelf life.
It is, however, unsuitable for food, pharmaceutical products or any goods with an expiry date, which require a FIFO or FEFO logic to ensure correct stock rotation, prevent waste and guarantee regulatory compliance. The choice of physical storage system must therefore always be consistent with the valuation method adopted and with the specific characteristics of the products handled.
Want to optimise your inventory management with the method best suited to your business? Contact us
There is no universally valid inventory management method: the right choice depends on the type of products, handling volumes, the regulatory context and the company’s strategic objectives. Adopting the wrong method, or applying it without consistent design of processes and storage areas, can lead to operational inefficiencies, distorted accounting results and a higher risk of obsolescence. Our logistics consultants are available to analyse your specific situation and help you define the most efficient inventory management system for your business.
Contact us for an initial consultation: together we will assess the available options and identify the solution that best meets your operational and tax needs.